Mediterranean Europe Ref. CY-01
Cyprus
A 60-day non-dom regime aimed squarely at internationally mobile earners.
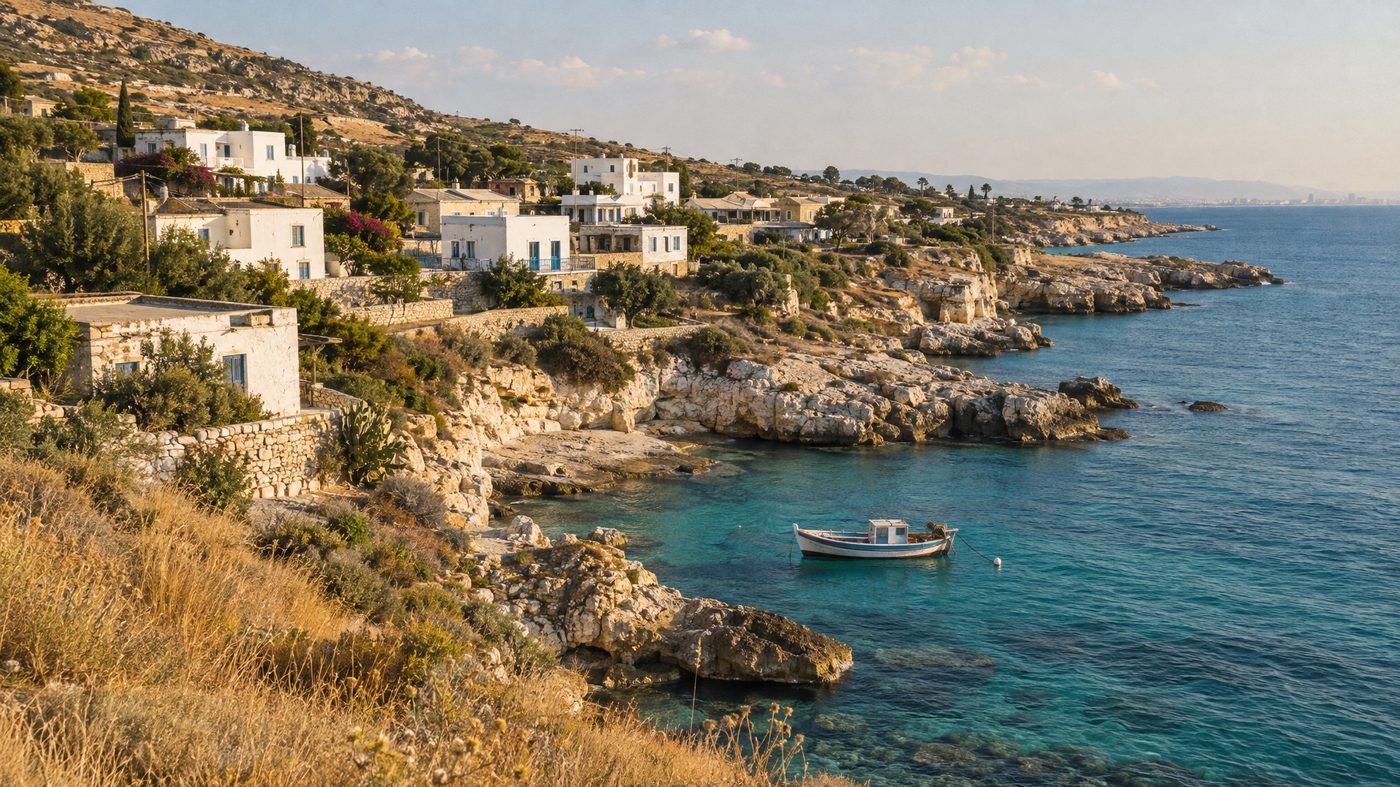
Illustrative image — AI-generated, not a photograph of the actual location
Overview
A 60-day non-dom regime aimed squarely at internationally mobile earners.
Cyprus is the jurisdiction to consider when the objective is EU residency with a light presence requirement and favourable treatment of investment income. The permanent residency programme is comparatively inexpensive and processes quickly; the non-dom regime exempts dividend and interest income for seventeen years from first residency.
The 60-day tax residency rule is the distinctive feature. Under specific conditions — no more than 60 days in any other single country, at least 60 days in Cyprus, employment or business in Cyprus, and tax residence nowhere else — an individual can become Cypriot tax resident while spending most of the year elsewhere. Paired with non-dom status, that combination is unusually efficient for people whose income is dividend- and interest-heavy.
Two corrections to the popular version of this story. First, the citizenship-by-investment programme was closed in 2020 after the disclosure of due-diligence failures; it is not available, and any offer of it is fraudulent. Second, the 60-day rule is condition-heavy: if you are tax resident anywhere else, it does not apply. It is a tool for people who genuinely have no other tax home, not a loophole for people with one.
Cyprus also carries a genuine operational advantage in corporate structuring — a 12.5% corporate rate, an extensive treaty network, and a well-developed professional services sector. It carries a corresponding watchout: the 2013 banking crisis, which imposed losses on large depositors, is a reminder that bank-deposit concentration deserves careful thought.
How it scores
Editorial scores, 1–5, on a consistent basis across the index. 5 is favourable (low tax, strong mobility, fast, cheap, low presence). They are a comparison aid, not a recommendation, and they weight nothing — that is what the finder does.
Routes currently available
Timelines are indicative ranges for a complete, well-documented application and are frequently extended by administrative backlog. They are not guarantees.
Tax position
How Cyprus taxes you
Cyprus taxes residents on worldwide income, with non-dom individuals exempt from tax on dividends and interest for 17 years from first becoming resident. The 60-day rule can establish tax residency with limited presence if no other tax residence exists. Corporate tax is 12.5%. Social insurance and defence-contribution rules apply separately and should be modelled.
What works
Strengths
- 60-day tax residency under defined conditions — among the shortest triggers in the EU.
- Non-dom status exempts dividend and interest income for 17 years.
- Comparatively inexpensive permanent residency relative to other EU programmes.
- 12.5% corporate rate and an extensive double-tax treaty network.
What to watch
Risks and caveats
- The citizenship-by-investment programme closed in 2020. No legitimate route exists.
- The 60-day rule is void if you are tax resident anywhere else — conditions are strict and audited.
- Banking concentration risk is real: the 2013 crisis imposed losses on uninsured depositors.
- Non-dom relief is time-limited and applies to specific income types, not to all foreign income.
Compare
Other jurisdictions in the index.
 PT
Portugal
Narrowed golden-visa routes after 2023 — funds and income pathways remain.
 PA
Panama
Territorial taxation and a USD economy — the classic offshore base.
 AE
United Arab Emirates
No personal income tax; 9% corporate tax above the threshold.
Next step
Is Cyprus actually open to you?
Eligibility depends on your citizenship, income sources, family structure and timeline. An assessment tells you whether Cyprus is viable for your situation — and which routes are closed.